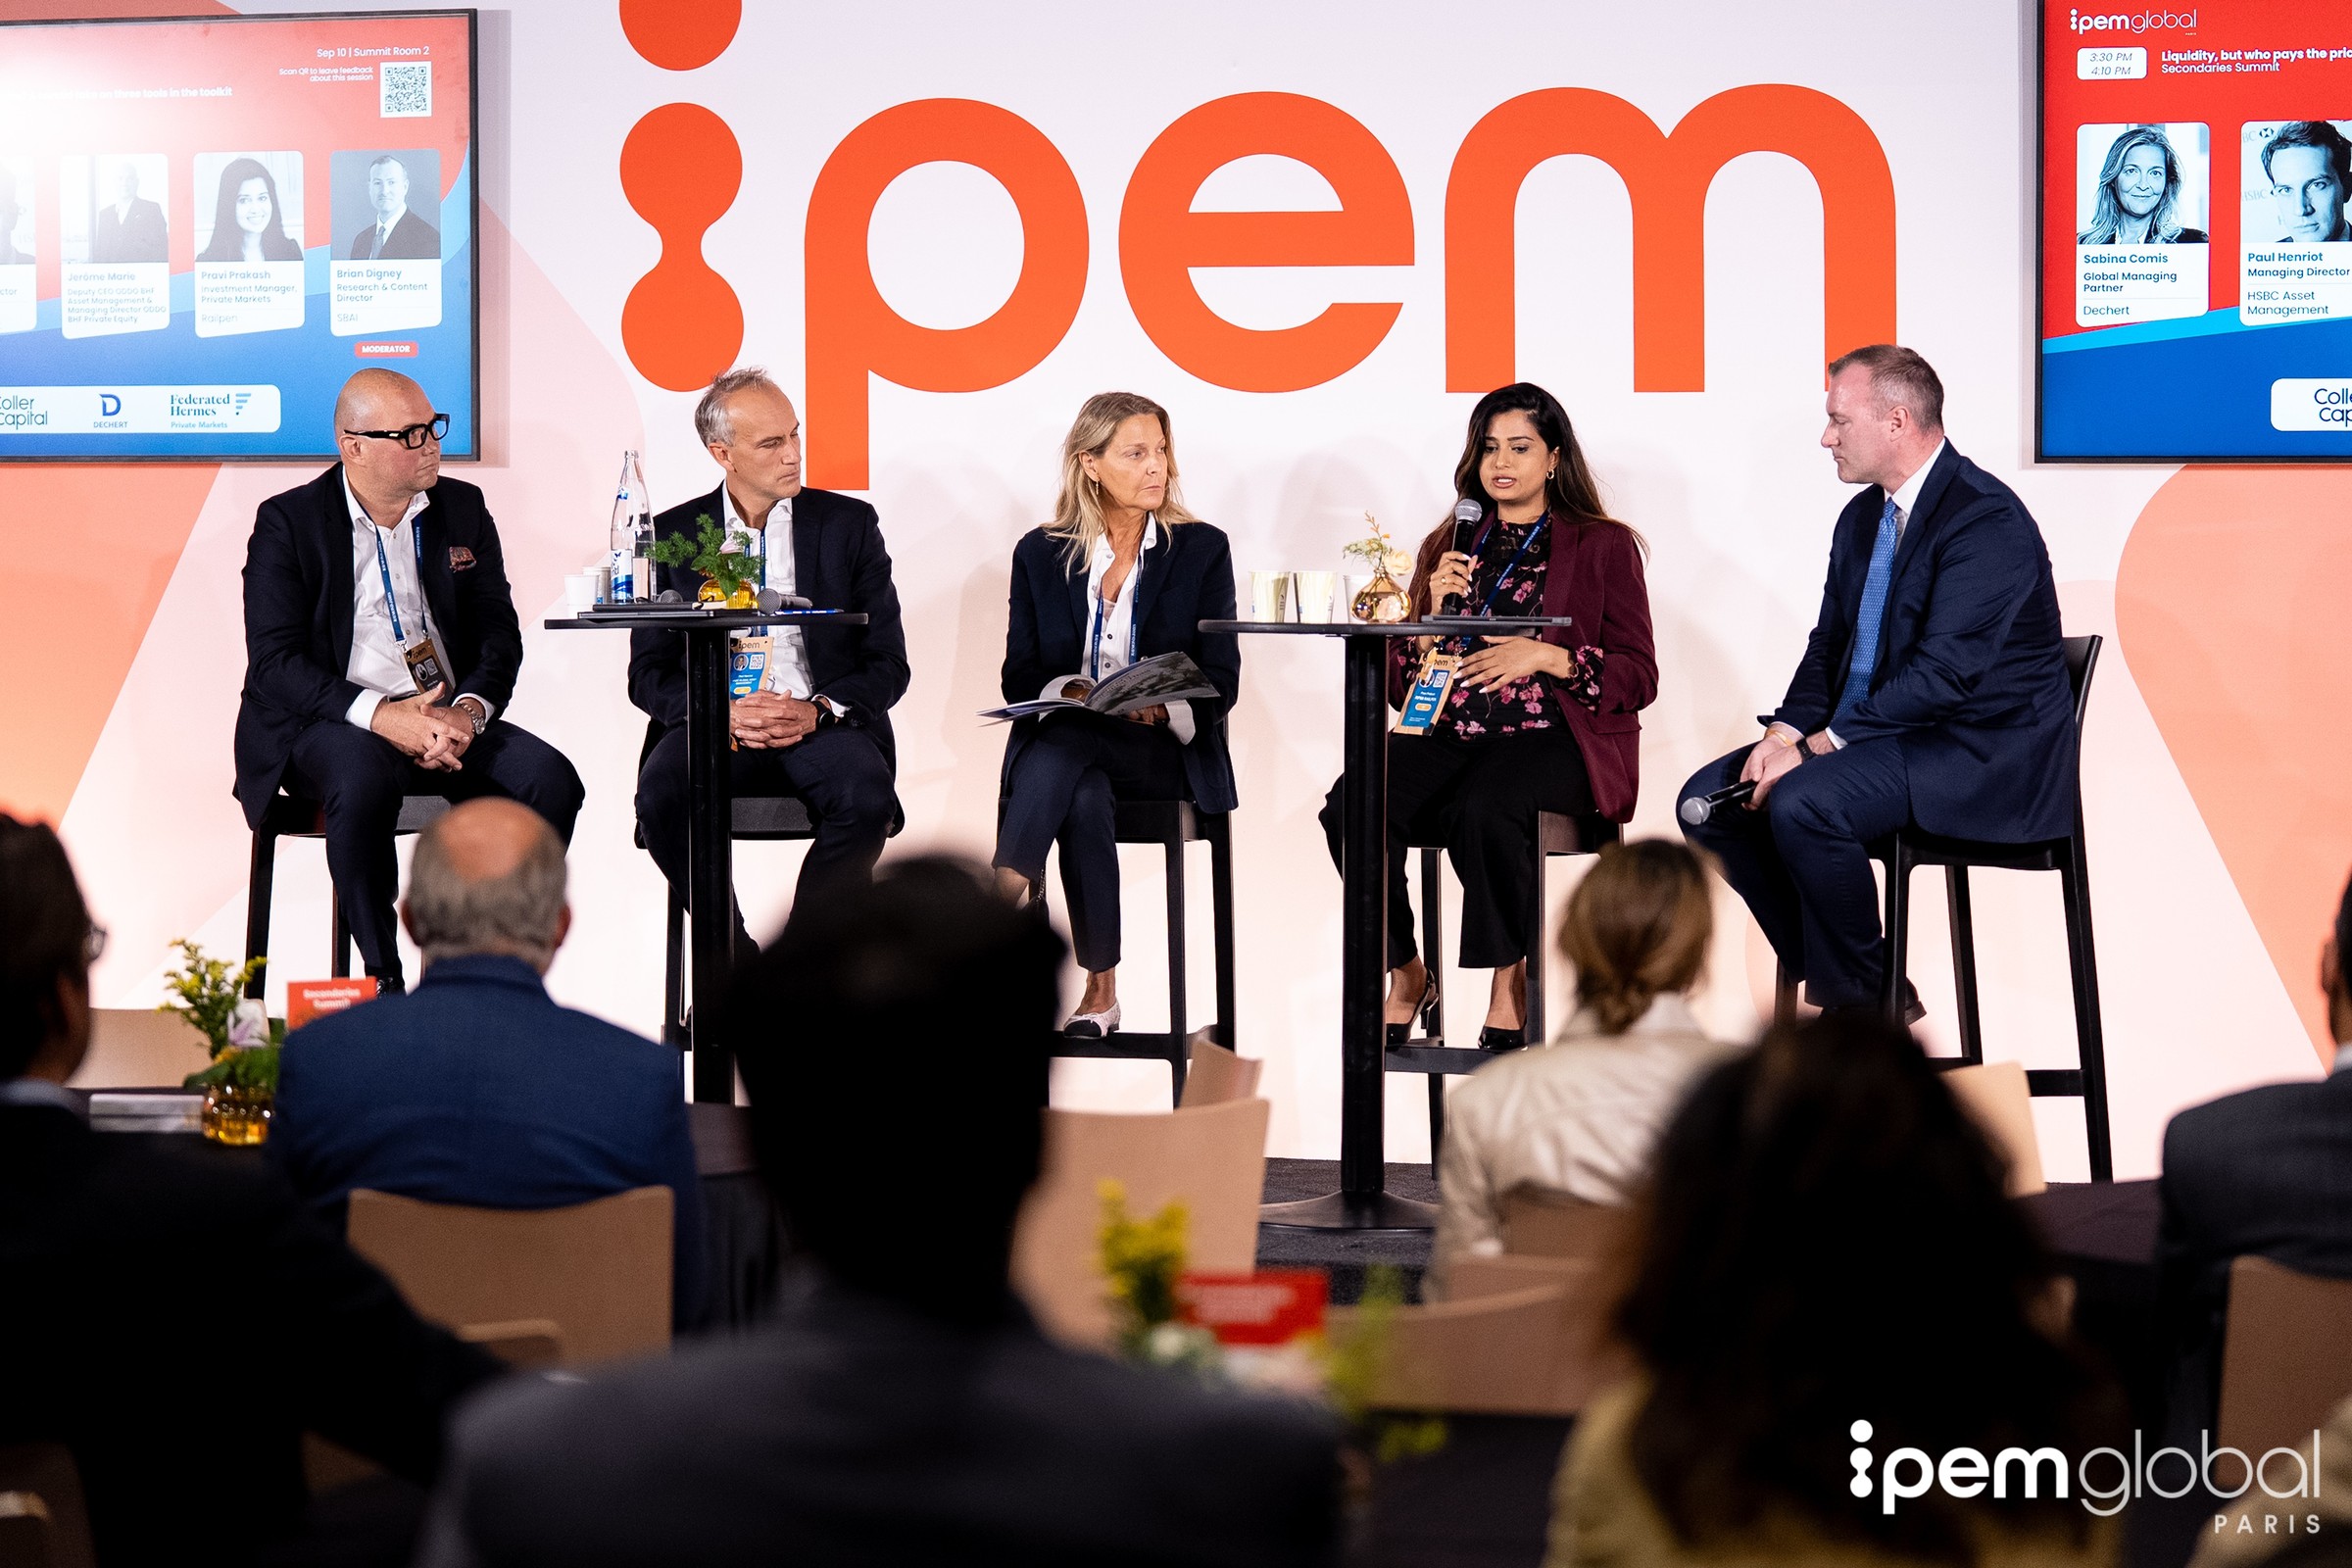
Paul Henriot, Managing Director, Capital Solutions Alternatives - HSBC GLOBAL ASSET MANAGEMENT
Jerome Marie, Senior MD - ODDO BHF
Pravi Prakash, Investment Manager, Private Markets - RPMI RAILPEN
Liquidity: from exception to standard toolkit
Liquidity solutions in private markets have moved from being viewed as exceptional or controversial to becoming a more established part of the investment toolkit. Continuation vehicles, NAV financing, subscription lines and related structures are now more widely accepted by institutional investors, supported by clearer use cases and greater discipline around proceeds. The growth of GP-led secondaries in particular reflects a structural shift, with these transactions increasingly used both to provide exits and to support longer-term value creation in high-quality assets. While demand for liquidity may fluctuate with market conditions, the broader acceptance of these tools appears durable. As a result, liquidity management is becoming an increasingly important element of portfolio construction and fund governance.
Liquidity transfers risk, it doesn’t remove it
Liquidity solutions can provide capital to sellers and improve portfolio flexibility, but they do not eliminate the underlying illiquidity of private-market assets. In many cases, these structures transfer illiquidity and risk from an outgoing investor to an incoming one, with price serving as the mechanism that balances certainty for the seller against risk absorption for the buyer.
NAV financing, for example, can provide cash to investors and improve headline distribution metrics, while the risk profile and duration of the underlying portfolio remain broadly unchanged. Similarly, continuation vehicles can create a liquidity event for exiting investors, but the assets themselves may remain held for a longer period under new ownership. A clear understanding of this trade-off is essential when assessing the true economic effect of any liquidity solution.
Continuation vehicles: choice needs governance
- Optionality is the core benefit
Continuation vehicles allow investors seeking cash to exit while those with conviction and a longer horizon can roll their exposure, enabling the manager to continue executing the value-creation plan.
- Process quality determines credibility
Transparent valuations, timely fairness opinions, access to data rooms and early engagement with LPs and LPACs are essential to a well-run continuation process.
- Conflicts must be managed, not assumed away
As the manager may determine timing, asset selection, economics and, in some cases, the bidder, effective governance is required to manage inherent conflicts of interest and maintain alignment across existing and incoming investors.
Alignment, transparency and price discovery
Effective liquidity solutions depend on clear alignment between general partners, existing investors and incoming capital. Transparent price discovery, equal access to information, timely fairness opinions and early engagement with LPs and LPACs help mitigate concerns around valuation, conflicts of interest and process integrity. Where these safeguards are applied consistently, liquidity tools are more likely to be viewed as credible mechanisms for managing portfolios rather than as sources of contention. As the market matures, stronger governance and clearer communication will remain central to maintaining trust across all stakeholders.
Liquidity needs to be understood, not just promised
Liquidity solutions are becoming more widely used, but their costs and benefits are not evenly distributed across market participants. Tools such as continuation vehicles, NAV financing, GP stakes and strip sales serve different purposes: some provide liquidity to investors, others support portfolio financing, firm growth or capital recycling. The effectiveness of each depends on whether the transaction is structured with clear alignment, transparent pricing and appropriate governance. As these mechanisms become more established, scrutiny is likely to focus increasingly on their true cost, who ultimately bears it and whether the benefits are shared fairly among general partners, outgoing investors and incoming capital.
Who pays the price for liquidity?
Liquidity solutions are becoming more widely used, but their costs and benefits are not evenly distributed across market participants. Tools such as continuation vehicles, NAV financing, GP stakes and strip sales serve different purposes: some provide liquidity to investors, others support portfolio financing, firm growth or capital recycling. The effectiveness of each depends on whether the transaction is structured with clear alignment, transparent pricing and appropriate governance. As these mechanisms become more established, scrutiny is likely to focus increasingly on their true cost, who ultimately bears it and whether the benefits are shared fairly among general partners, outgoing investors and incoming capital.
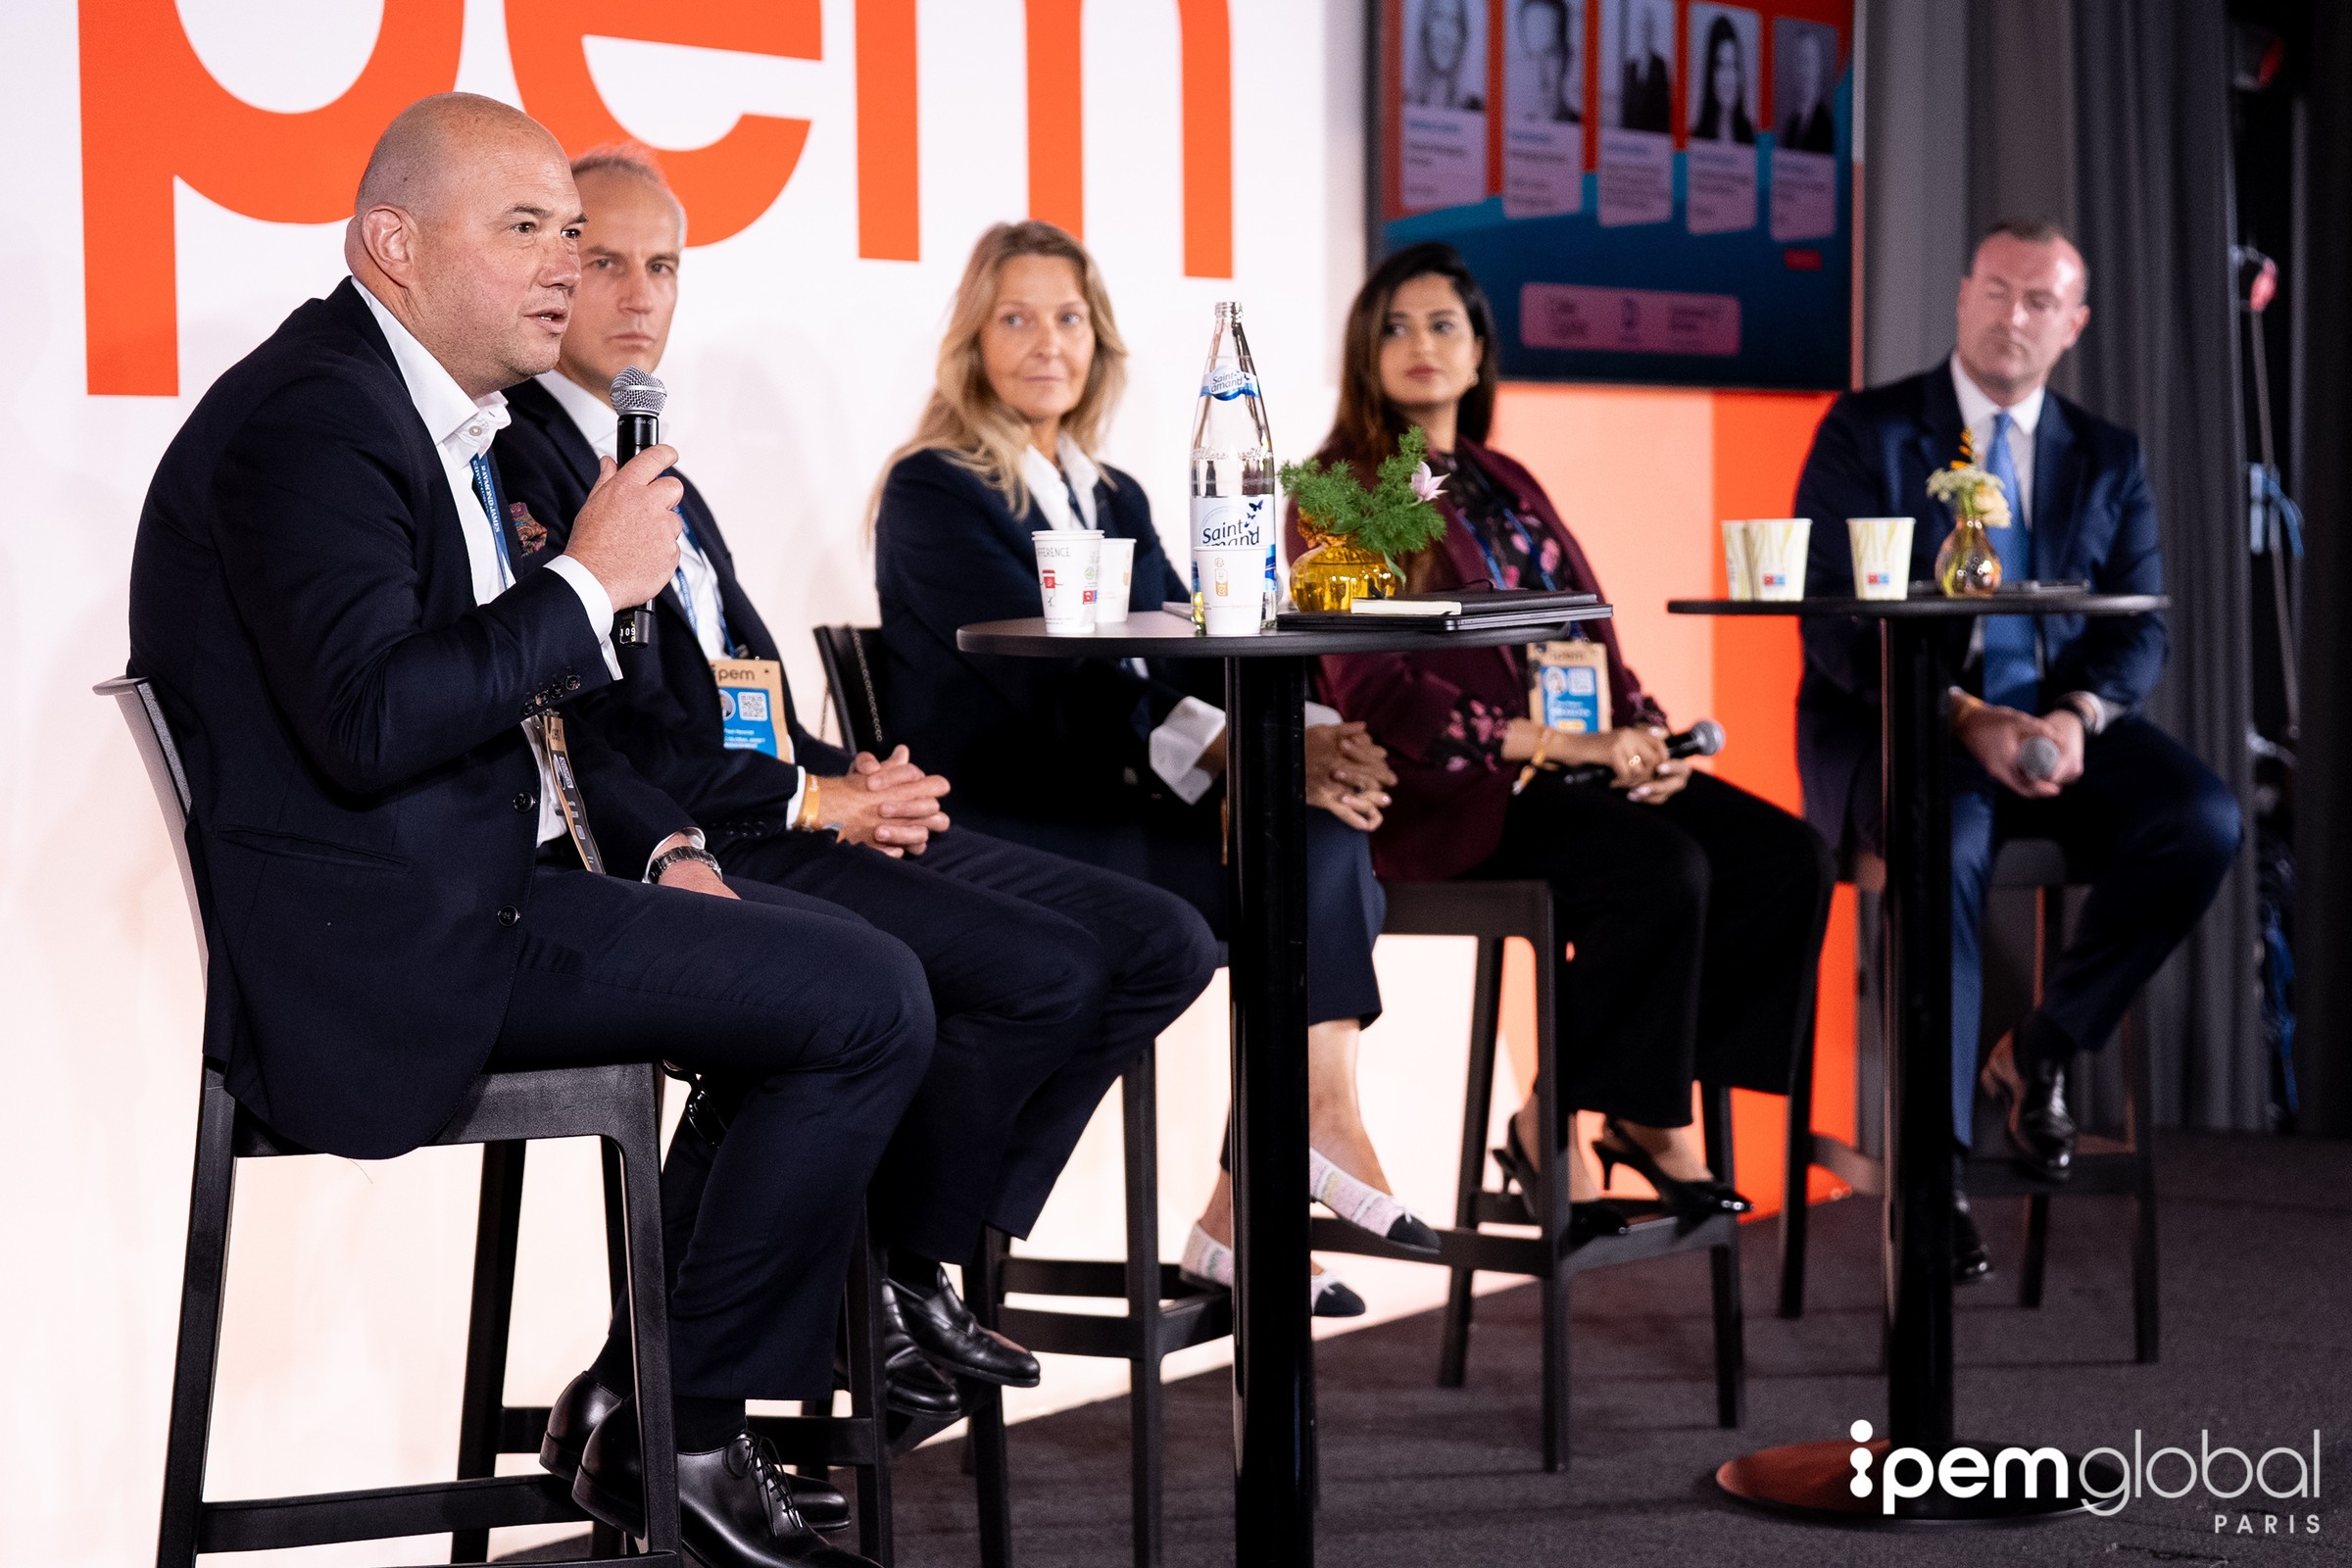
Speaker Quotes
“We get 20 days to make our decision if we want to roll or liquidate, and the valuation at which we’re offered the liquidation option is not always transparent, acceptable, or evidenced enough.” Pravi Prakash, RPMI RAILPEN
“Governance doesn’t eliminate the conflict of interest. It just manages well the conflict of interest.” Jerome Marie, ODDO BHF
“The market has done a lot of things to make sure those tools now are used in a healthier manner… This is about how healthy the industry is, and so the ecosystem needs to be better at doing this.” Sabina Comis, DECHERT LLP
“They hear liquidity; they will not go into the fine print. So that’s where you have, in my view, the biggest risk.” Paul Henriot, HSBC GLOBAL ASSET MANAGEMENT